
 Español
 Türkçe
 Français
 عربي
 dansk
 한국어
 Deutsch
 Việt Nam
 Italiano
 日本語
 Português

Reporting period: November 9–15, 2026
WEEK 46 / BUYER BRIEF
China's steel market moved slightly lower during Week 46. The Mysteel national steel price index fell 0.43% week on week, while supply and apparent consumption of the five major steel products both eased. Total inventory declined by 1.7%, indicating continued destocking, but the simultaneous slowdown in demand does not confirm a broad demand-led rebound. For overseas buyers, the signals are mixed: October steel exports were 9.854 million tonnes (+0.7% YoY), container freight benchmarks softened overall, and lower coke prices reduced part of the raw-material cost base. Trade-remedy developments reported for Saudi Arabia and Thailand warrant monitoring for affected product categories.
At a Glance
STEEL PRICE INDEX
3,386
−0.43% week on week
TOTAL INVENTORIES
13.5629m t
−1.7% week on week
APPARENT CONSUMPTION
8.2618m t
−0.4% week on week
SCFI
3,572.33
−1.68% week on week
OCTOBER STEEL EXPORTS
9.854m t
+0.7% year on year
THIRD COKE PRICE CUT
RMB 50–55/t
Took effect November 13
| Key indicator | Week 46 reading | Buyer relevance |
|---|---|---|
| China October total exports | +35.2% YoY in USD terms | Headline export growth; not the steel-export growth rate. |
| China steel exports | 9.854 Mt; +0.7% YoY | Direct steel exports were broadly stable year on year. |
| Mysteel national steel price index | 3,386; -0.43% WoW | Broad benchmark edged lower. |
| Five-product inventory | 13.5629 Mt; -1.7% WoW | Stocks fell, although demand also softened. |
| 47-port imported iron ore stocks | 177.5947 Mt; +2.2627 Mt WoW | Port-side availability increased. |
| SCFI composite | 3,572.33; -1.68% WoW | Container benchmark declined for a second week. |
| Third coke price cut | RMB 50–55/t on Nov 13 | Reduced one part of the steelmaking cost base. |
CONTENTS
1. China Steel Market: Prices and Supply-Demand Balance
The national steel price index and the main product averages declined modestly. Both long products and flat products recorded lower index readings, while rebar and hot-rolled coil (HRC) averages also edged down.
| Price indicator | Week 46 level | Weekly change |
|---|---|---|
| Mysteel national steel price index | 3,386 | -15 points (-0.43%) |
| Long-products index | 3,427 | Lower WoW |
| Flat-products index | 3,348 | Lower WoW |
| National rebar average | RMB 3,295/t | -RMB 11/t |
| National HRC average | RMB 3,209/t | -RMB 14/t |
| Rebar futures close | RMB 3,035/t | Reported closing level |
| HRC futures close | RMB 3,179/t | Reported closing level |
| Iron ore futures close | RMB 669.5/t | Reported closing level |
The five major steel products recorded weekly supply of 8.0265 million tonnes, down 0.3%. Apparent consumption was 8.2618 million tonnes, down 0.4%. Construction-steel consumption fell 1.3%, while flat-product consumption was broadly stable. This points to a market in which supply and demand were both easing.
For buyers, falling inventories can support prices, but when consumption is also slowing, destocking alone does not confirm a sustained recovery. Buyers should compare current offers with their required delivery window instead of treating one weekly movement as a definitive trend.
For structural and long-product requirements, explore Promisteel's Hot Rolled Steel range and
H-beam products for specification-based enquiries.
2. Raw Materials and Steelmaking Costs
Raw-material signals were mixed. A third round of coke price reductions took effect on November 13, with mills in Hebei and Shandong lowering purchase prices by RMB 50–55 per tonne. The report puts cumulative reductions since October at RMB 250–275/t. This eases one component of steelmaking costs, although the effect on individual mills depends on purchasing contracts, inventory position and product mix.
| Raw-material / operating indicator | Week 46 reading | Weekly movement/note |
|---|---|---|
| Coke purchase price | Third reduction landed Nov 13 | RMB 50–55/t cut; cumulative RMB 250–275/t since October |
| Anze low-sulfur prime coking coal | RMB 2,210/t | Down RMB 20/t |
| Coke futures close | RMB 1,970/t | +1.4% WoW |
| Coking coal futures close | RMB 1,439/t | +2.0% WoW |
| Daily hot metal output | 2.3032 Mt | Down 37,000 t; fifth consecutive weekly decline |
| BF operating rate at 247 mills | 79.71% | Unchanged |
| Hot-metal capacity utilization | 86.48% | Down 0.14 percentage points |
| Independent EAF capacity utilization | 60.81% | Up 1.03 pp; average reported loss RMB 53/t |
Imported iron ore inventories at 47 ports increased by 2.2627 million tonnes to 177.5947 million tonnes. Global iron ore shipments also rose, while daily port offtake eased. This indicates greater port-side availability in the short term, although mill-side inventories and actual consumption remain important.
Buyers of flat steel and coated products should assess the delivered specification and quotation validity rather than infer a direct product-price reduction from lower coke costs. Raw-material mix, mill order books, coating costs, processing requirements and freight all influence final offers.
3. Ocean Freight and Export Logistics
The Shanghai Containerized Freight Index (SCFI) composite declined 1.68% week on week to 3,572.33, its second consecutive weekly fall. The report describes weaker post-holiday cargo momentum and carrier discussions around December general rate increases. Route-level movements were mixed: Europe and US routes declined, while the Mediterranean route increased.
| Freight benchmark / route | Week 46 level | WoW change |
|---|---|---|
| SCFI composite | 3,572.33 points | -1.68% (-61.12 points) |
| SCFI Europe | USD 2,291/TEU | -1.46% (-USD 34) |
| SCFI Mediterranean | USD 3,619/TEU | +6.66% |
| SCFI US West Coast | USD 7,111/FEU | -3.66% (-USD 270) |
| SCFI US East Coast | USD 9,387/FEU | -4.77% (-USD 470) |
| Baltic Dry Index (BDI) | 2,980 points | +4.4% |
| Baltic Capesize Index (BCI) | 4,719 points | +5.8% |
| Baltic Panamax Index (BPI) | 2,118 points | +4.0% |
Buyers shipping containerized coils or sheets should request a current route-specific freight quotation rather than apply the SCFI composite directly to an individual shipment. Buyers moving bulk cargo should assess the relevant vessel and cargo basis separately.
A landed-cost comparison should include the product price, inland transport, port charges, ocean freight, insurance where applicable, destination charges and Incoterm. Confirm the quotation validity period and whether surcharges or seasonal adjustments may apply.
For coated steel enquiries, review Promisteel's Galvanized and Coated Steel range and include destination port, shipment quantity and preferred Incoterm in the RFQ.
4. Trade Policy: Developments Buyers Should Monitor
The Week 46 source report highlights several trade-remedy developments. These items should be checked against the relevant investigating authority's official notice before being used for a legal or customs determination.
| Development reported in the brief | Products / scope described | Potential buyer action |
|---|---|---|
| Saudi Arabia: AD investigation opened Nov 9 (AD-26-3) | Hot-rolled light and medium sections from China and Türkiye, including H-beams, angles and channels | Confirm scope, origin rules, investigation timeline and exporter response requirements using the official notice. |
| Thailand: first sunset review initiated Nov 13 | Tin-plated steel sheet/coil; existing Chinese-origin rates reported at 2.45%–17.46% | Check exact product codes, exporter-specific rate, review schedule and continued application of existing measures. |
| EU: definitive duties reported Nov 13 | Cold-rolled flat steel from five origins; report gives 3%–27.9% and says China was not a respondent | Check the published regulation, covered origins, product definition and customs classification. |
An investigation, a sunset review and a definitive duty decision have different legal effects and timelines. Opening an investigation does not mean a final duty has already been imposed.
The Thailand development is relevant to tinplate buyers. Before placing or renewing an order, confirm the exact product description and customs code with the importer or customs broker. Promisteel's tinplate product information may support a technical discussion, but it does not replace tariff classification or trade-remedy advice.
5. Inventory and Product-Level Signals
Total inventory across the five major steel products fell by 235,300 tonnes, or 1.7%, to 13.5629 million tonnes. Social inventory decreased by 229,400 tonnes, while mill inventory increased by 5,900 tonnes. Apparent consumption declined by 0.4%, showing that inventory reduction continued as demand softened.
| Inventory/production indicator | Week 46 level | WoW change |
|---|---|---|
| Five-product weekly supply | 8.0265 Mt | -0.0224 Mt (-0.3%) |
| Five-product total inventory | 13.5629 Mt | -0.2353 Mt (-1.7%) |
| Five-product apparent consumption | 8.2618 Mt | -0.0367 Mt (-0.4%) |
| Rebar weekly output | 1.8282 Mt | -0.0308 Mt (-1.7%) |
| Rebar total inventory | 4.6604 Mt | -0.1633 Mt (-3.4%) |
| HRC weekly output | 2.9251 Mt | +0.0123 Mt (+0.4%) |
| HRC total inventory | 4.1944 Mt | -0.0287 Mt (-0.7%) |
| 47-port imported iron ore stocks | 177.5947 Mt | +2.2627 Mt |
| 16-port imported coking coal stocks | 7.6177 Mt | +0.1549 Mt |
| Tangshan billet inventory | 1.7513 Mt | +0.0488 Mt |
The product split matters. Rebar output and inventory both declined, while HRC output edged higher and HRC inventory declined only modestly. The report gives HRC apparent demand at 2.9538 million tonnes, down 17,900 tonnes.
For HRC-based products, including galvanized, coated and pipe-making feedstock, availability should be assessed by product, grade, thickness and delivery window. Broad national inventory figures cannot establish availability of a specific specification.
Buyers sourcing feedstock can explore Hot Rolled Steel and
6. Procurement Implications for Overseas Buyers
Separate headline export growth from steel-export growth
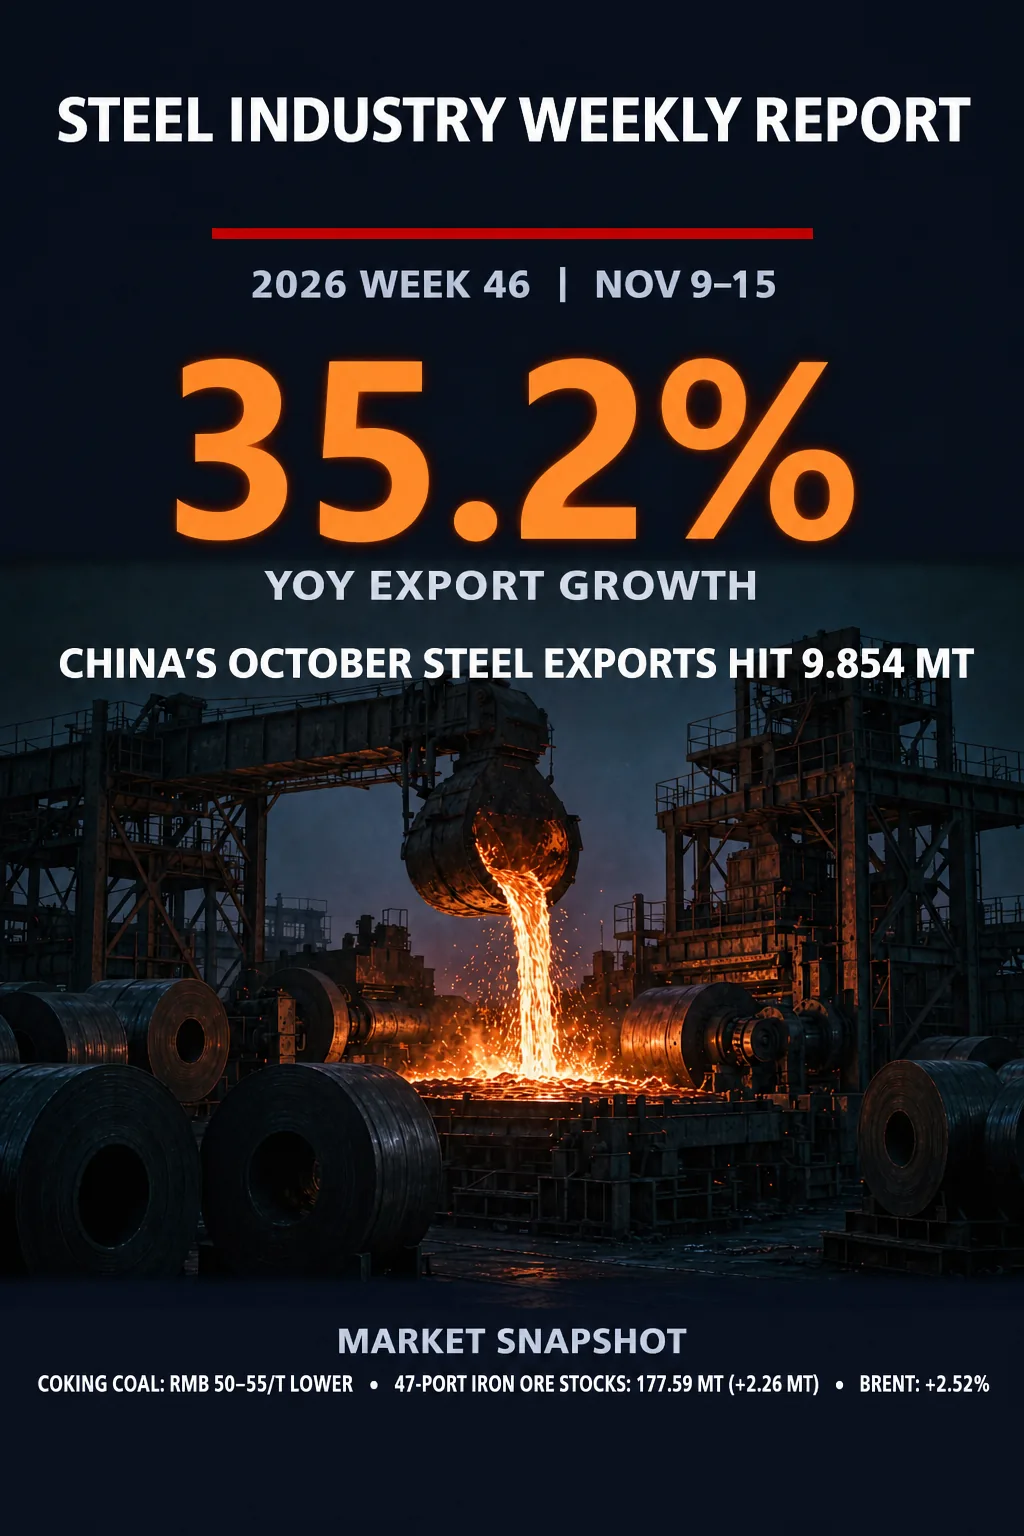
China's total exports in October increased 35.2% year on year in US-dollar terms, according to the report. This is a headline figure for total exports, not the growth rate for steel exports. The report separately records October steel exports at 9.854 million tonnes, up 0.7% year on year. Keep these two indicators distinct.
Compare offers on a like-for-like basis
A lower market benchmark does not mean every grade or processed product should be cheaper by the same percentage. Compare offers using the same standard, grade, thickness, width, coating, surface finish, quantity, packaging, inspection scope, Incoterm and delivery window.
Build freight into the landed-cost comparison
The SCFI declined overall, but route movements differed. Request a current freight quotation for the actual destination and shipment plan. Confirm container type, payload limits, loading method, moisture protection, and destination charges.
Check trade-remedy exposure before shipment
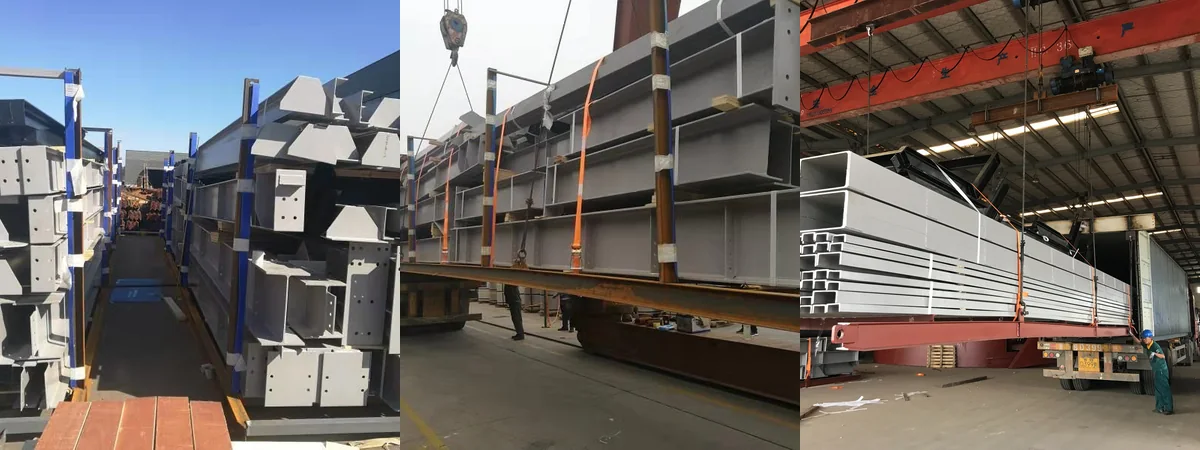
For H-beams, angles, channels and tinplate, confirm the current trade-policy position for the destination market. Country of origin, product description, tariff code, specification and exporter identity can affect the applicable treatment.
Use a complete RFQ
| RFQ field | Information to provide |
|---|---|
| Product | Product name and intended application |
| Standard and grade | Applicable ASTM, EN, JIS, GB or project-specific standard and grade |
| Dimensions | Thickness, width, length or coil dimensions; tolerances if specified |
| Surface / coating | Surface finish, coating type and coating mass where applicable |
| Quantity | Total tonnage, order split and shipment schedule |
| Quality documents | MTC, inspection requirements, test reports and traceability needs |
| Packing | Export packing, moisture protection, marking and loading requirements |
| Delivery | Destination port, Incoterm and required delivery window |
A structured RFQ helps suppliers assess the specification and logistics together. Buyers of structural products can also review Promisteel's Structural Steel range and
7. Outlook and Risk Factors
The Week 46 report characterizes the near-term market as rangebound with a slightly weaker bias. The main supportive factor is continued destocking across the five major steel products, including lower rebar inventory. Pressures include softer apparent consumption, lower coke prices, rising imported iron ore stocks and a firmer US-dollar environment as described in the source brief.
| Factor | Direction in source report | Why it matters |
|---|---|---|
| Five-product inventory continues to fall | Supportive | Lower stocks can provide a buffer against further price declines. |
| Hot metal output falls for a fifth week | Neutral to slightly supportive | Lower production partly offsets seasonal demand weakness. |
| October total exports grow 35.2% YoY | Supportive for trade sentiment | This is total exports; steel exports separately rose 0.7%. |
| Third coke price reduction lands | Negative for cost support | Lower input costs can reduce the steel-price cost floor. |
| 47-port iron ore stocks rise 2.2627 Mt | Negative for iron ore pricing | Higher port stocks indicate greater near-term availability. |
| Tangshan billet inventory rises | Negative | Higher billet stocks may pressure billet and rerolling markets. |
| Saudi section-steel investigation reported | Trade risk | Affected exporters should review official scope and procedure. |
| Freight benchmarks diverge by route | Mixed | Route-specific freight and shipment timing remain important. |
This outlook is not a price guarantee. Actual transaction prices depend on product type, grade, mill, order size, processing, delivery terms and destination-market conditions. Use weekly indicators as context, then request current quotations against a complete specification.
8. Frequently Asked Questions
Did China's steel exports rise by 35.2% in October 2026?
No. The 35.2% figure refers to China's total exports in US-dollar terms. The report separately gives October steel exports as 9.854 million tonnes, up 0.7% year on year.
What happened to Chinese steel prices in Week 46?
The Mysteel national steel price index fell 0.43% week on week to 3,386. The reported national averages were RMB 3,295/t for rebar and RMB 3,209/t for HRC.
Did China's steel inventories increase or decrease?
The total inventory of the five major steel products declined by 235,300 tonnes, or 1.7%, to 13.5629 million tonnes. Social stocks fell while mill stocks edged higher.
Why did coke prices matter this week?
A third round of coke price reductions took effect on November 13 at RMB 50–55/t. Cumulative reductions since October were reported at RMB 250–275/t, easing part of the steelmaking cost base.
Were container freight rates lower in Week 46?
The SCFI composite declined 1.68% to 3,572.33. Europe, the US West Coast and US East Coast fell, while the Mediterranean route increased.
What trade-policy change should tinplate buyers watch?
The report says Thailand initiated a first sunset review of duties on tin-plated steel sheet/coil from China on November 13, with existing rates reported at 2.45%–17.46%. Verify the official notice, product scope and applicable rate before shipment.
Does the Saudi anti-dumping investigation mean a final duty has been imposed on Chinese H-beams?
No. Opening an investigation is not the same as a final duty decision. The report describes a probe opened on November 9 covering certain hot-rolled sections. Check the official case documents and timetable.
What should an overseas buyer include in a steel RFQ?
Include product, standard, grade, dimensions and tolerances, coating or surface requirements, quantity, quality documents, inspection scope, packing, destination port, Incoterm and required delivery window.
About Promisteel
Promisteel supplies steel products and sourcing support for international buyers across construction, manufacturing and industrial applications. Buyers can discuss product specifications, processing requirements, quality documentation, export packing and shipment arrangements with the Promisteel team.
Explore Steel Industry News


